Home › Knowledge › Medicare Advantage
Best Medicare Advantage Plans in Illinois (November 2026)
Vedanth Bhartee
Writer · Reviewed by Richard ChanUpdated Jun 12, 2026
13 min read
Key Takeaways
Medicare Advantage plans in Illinois provide an alternative to Original Medicare by bundling Part A and Part B benefits into plans administered by private insurers.
Many Illinois plans include integrated Part D prescription drug coverage as well as supplemental perks like dental, vision, and fitness programs.
Plan costs, provider networks, and specific benefits vary by Illinois county, requiring beneficiaries to select plans based on their local availability and healthcare needs.
Navigating your health coverage in retirement shouldn't feel like a shot in the dark. Medicare Advantage (widely recognized as Medicare Part C) plans are designed to deliver every core benefit included in Original Medicare (Part A and Part B), but they go a crucial step further. These bundled plans frequently bake in essential prescription drug coverage alongside highly sought-after extras like dental, vision, and hearing benefits. Because of this all-in-one approach, Medicare Advantage has surged in popularity among savvy retirees looking to protect both their health and their life savings.
If you live in Illinois, you are surrounded by a deeply competitive, robust marketplace of Medicare Advantage options. But with so many national and regional insurance titans actively fighting for your business, cutting through the aggressive marketing noise to find a plan that genuinely fits your medical needs and fixed income is absolutely vital.
Illinois is home to a massive selection of Medicare Advantage plans backed by established, reputable carriers. To strip the confusion out of your decision, we focus ruthlessly on the metrics that matter most: ironclad drug coverage, verified member satisfaction, and actual, bottom-line costs. Below, we break down the hard data on top providers in the state, clearly outlining their median monthly premiums and out-of-pocket maximums.
Compare Medicare Advantage Providers in Illinois
Before we dive into the specific statistics for Illinois’s leading Medicare Advantage providers, it is critical to understand the key benchmarks you must use to evaluate any health plan:
CMS Star Rating: Released annually by the Centers for Medicare & Medicaid Services (CMS), this rating is an objective measure of the real-world quality of care and customer service a plan delivers. Scored from 1 (poor) to 5 (excellent) stars, this rigorous system evaluates up to 40 distinct performance metrics. It is your best defense against subpar providers.
Monthly Premium: This is the fixed, baseline dollar amount you must pay the insurance company every single month just to keep your coverage active, regardless of whether you visit a doctor.
In-Network Max Out-of-Pocket Amount: This is your ultimate financial safety net. It represents the absolute maximum amount of your own money you will be forced to spend on covered, in-network medical services over the course of a single calendar year. If you hit this limit, the plan pays 100% of your covered costs.
Note: All statistics presented in the charts below are calculated using hard data strictly isolated to the state of Illinois.
National Providers
| Provider Name | Average CMS Star Rating | Median Monthly Premium | Median In-Network Max Out-of-Pocket $ |
| UnitedHealthcare | 4.1⭐ | $0.00 | $3,800 |
| Humana | 4.2⭐ | $0.00 | $5,500 |
| Aetna | 4.0⭐ | $0.00 | $4,390 |
| Blue Cross and Blue Shield | 2.9⭐ | $0.00 | $5,900 |
| Wellcare | 2.8⭐ | $0.00 | $2,900 |
Regional Providers
| Provider Name | Average CMS Star Rating | Median Monthly Premium | Median In-Network Max Out-of-Pocket $ |
| Essence Healthcare | 5.0⭐ | $0.00 | $2,800 |
| Medica | 4.5⭐ | $0.00 | $3,900 |
| Quartz Medicare Advantage | 4.5⭐ | $30.00 | $4,500 |
| HealthPartners UnityPoint Health | 4.5⭐ | $24.50 | $3,600 |
Please be aware: while regional providers often boast incredibly high CMS ratings (like 5 stars), they inherently operate with much smaller, localized networks of doctors and hospitals compared to the massive national carriers. You must verify that your preferred doctors are actually in-network.
Top-Rated Medicare Advantage Providers in Illinois
Humana
Humana is an established behemoth in the American health insurance sector, delivering a vast portfolio of healthcare products tailored for seniors.
Nationally, Humana is the second largest provider of Medicare Advantage plans, commanding a massive 17% of the total U.S. market share and offering deep, reliable networks.
Blue Cross and Blue Shield of Illinois
Blue Cross and Blue Shield of Illinois (BCBSIL), operating under the Health Care Service Corporation umbrella, is the only statewide, customer-owned health insurer in Illinois. They dominate the state's health benefits landscape, fiercely protecting over 8.9 million members across all 102 Illinois counties.
In the specialized Medicare Advantage space, BCBSIL stands as the 5th largest carrier in the state, holding a 4% market share.
Essence Healthcare
Essence Healthcare, a subsidiary of Lumeris, holds a unique and prestigious distinction: it is the only Medicare Advantage plan in Illinois to achieve a perfect 5-star CMS rating.
Created in 2003 by a dedicated coalition of St. Louis-area physicians, Essence has rapidly evolved into a premier Medicare Advantage option across both Missouri and Illinois, proudly serving over 64,000 members as of 2020.
United Healthcare
UnitedHealthcare is an absolute giant in the health insurance industry. They are the undisputed national market leader (28.5%) in the Medicare Advantage sector, covering over 9 million American retirees. This dominance is mirrored in Illinois, where they capture a staggering 33% of the state's MA market.
Furthermore, UnitedHealthcare is rapidly expanding. They grew their MA footprint by 12.7% from 2022 to 2026, easily outpacing Humana, their closest competitor, which grew at 10.1%.
Aetna
Aetna, operating as a powerhouse subsidiary of CVS Health Corporation, delivers robust health insurance products nationwide.
As of early 2026, Aetna holds the title as the third-largest provider of Medicare Advantage plans (with a 10.6% market share) and totally dominates the standalone Medicare prescription drug plan market, capturing 27.2% of that critical sector.
Medica
Established in 1975, Medica is a steadfast, non-profit health plan that provides vital coverage to nearly 1.5 million individuals. Medica’s impressive infrastructure includes a network of 100,000 providers, 25 care system partners, and 250 community partners. They actively support 166,000 Medicare and Medicaid enrollees across 12 different states.
Quartz Medicare Advantage
Quartz distinguishes itself by relentlessly focusing on local, community-integrated healthcare. Through a highly vetted provider network, they serve more than 350,000 members residing across southern and western Wisconsin, parts of Illinois, Iowa, and Minnesota.
To maintain close ties with their members, Quartz operates regional offices in Madison, Sauk City, and Onalaska, Wisconsin.
HealthPartners UnityPoint Health
Launched in 2015, HealthPartners UnityPoint Health (HPUH) is a strategic alliance that merges the deep insurance expertise of HealthPartners with the expansive clinical network of UnityPoint Health.
HealthPartners brings a clinical footprint of 8 hospitals, 55 primary care clinics, and 20 urgent care centers. UnityPoint Health adds a massive integrated system featuring over 400 physician clinics and 39 network hospitals. This powerful union has allowed HPUH to scale a highly respected, 4.5-star Medicare plan throughout Iowa and Illinois.
Wellcare
Wellcare is a sprawling healthcare enterprise dedicated to providing reliable insurance products to Americans in all 50 states. Medicare Advantage is a foundational pillar of Wellcare’s business, where they maintain a solid 4.3% national market share.
By 2026, Wellcare also solidified its position as the second-largest provider of standalone Prescription Drug Plans (PDPs), commanding 19.9% of the market. Like its major competitors, Wellcare leverages deep, established connections with hospitals and physicians across Illinois.
How to Choose the Best Medicare Advantage Plan
Choosing the right Medicare Advantage plan is one of the most critical financial and medical decisions of your retirement. Let’s break down the essential steps to ensure you choose a plan that actually protects you when you get sick.
From ruthlessly evaluating your daily medical needs to scrutinizing the fine print, our goal is to give you the confidence to navigate this complex market.
- Assess Your Healthcare Needs: Take a hard look at your reality. Audit your daily prescription drugs, forecast your required specialist visits, and factor in any upcoming surgeries or chronic care needs.
- Review Plan Options: Meticulously research the Medicare Advantage plans available in your specific zip code. Prioritize plans backed by financially stable, highly rated insurance carriers.
- Check Network Providers: Do not guess. Explicitly confirm that your trusted primary care doctors, necessary specialists, and preferred local hospitals are officially in-network. Out-of-network care can be financially devastating.
- Evaluate Drug Coverage: If you rely on life-saving medications, cross-reference your prescriptions with each plan’s exact formulary. Pay strict attention to tier pricing, copayments, coinsurance, and restrictive rules like step therapy.
- Consider Additional Benefits: Medicare Advantage plans often dangle extra perks like free dental cleanings, vision exams, or gym access. Weigh the actual, practical value of these perks against the plan's overall out-of-pocket costs.
- Examine Cost Structures: Do the math. Compare the monthly premiums, annual deductibles, copayments, and coinsurance side-by-side. Ensure the plan's cost structure aligns strictly with your fixed retirement budget.
- Check Star Ratings: Use the objective CMS Star Ratings as a tie-breaker. Plans boasting 4 or 5 stars consistently deliver superior clinical outcomes and fewer administrative headaches.
- Understand Plan Rules and Restrictions: Read the fine print. You must understand exactly how the plan operates—specifically, whether you are required to jump through hoops to get referrals before seeing a specialist.
- Review Out-of-Pocket Maximums: This is your financial firewall. Identify the plan’s hard annual limit on out-of-pocket spending to understand your absolute worst-case scenario if you face a major medical crisis.
- Get Personalized Assistance: You do not have to do this alone. Reach out to the experts at CoverRight. We will cut through the jargon and guide you safely through the enrollment process.
Remember, there is no “best” plan, only the best plan for you. Your optimal choice depends entirely on your unique health profile and budget. If you are feeling overwhelmed, we strongly urge you to schedule a free consultation with one of our licensed insurance agents.
Additionally, if skyrocketing drug costs are squeezing your budget, proactively ask your doctor about generic alternatives. Switching to a generic version can easily save you thousands of dollars a year.
What Medicare Advantage Plans Cover
Medicare Advantage plans (officially known as Medicare Part C) are strictly regulated, private alternatives approved by the federal government.
By law, these private plans must deliver every single benefit mandated by Original Medicare (Part A and Part B). But they rarely stop there. Here is an unflinching look at what a standard Medicare Advantage plan actually covers:
- Hospital Coverage (Part A): This handles catastrophic care, including inpatient hospital stays, vital recovery time in skilled nursing facilities, compassionate hospice care, and specific, approved home health services.
- Medical Coverage (Part B): This covers your day-to-day healthcare survival, including outpatient treatments, routine doctor visits, essential preventive screenings, and certain home health care needs.
- Prescription Drug Coverage (Part D): The vast majority of Medicare Advantage plans bundle prescription drug coverage directly into the policy. If they do not, you are usually forced to purchase a standalone Part D plan to avoid crushing pharmacy bills.
- Additional Benefits: Depending on the specific carrier, MA plans frequently offer vital benefits that Original Medicare ignores—such as routine dental exams, vision hardware, hearing aids, fitness memberships, and targeted wellness programs.
- Out-of-Pocket Maximums: Unlike the dangerous, uncapped exposure of Original Medicare, Advantage plans include a strict, legally mandated yearly cap on your medical spending. Once you hit that number, the plan pays 100%.
However, never forget this critical rule: you must continue to pay your standard Medicare Part B monthly premium directly to the government, even if your Medicare Advantage plan advertises a "$0 premium." Always review the plan’s official Summary of Benefits document before signing anything.
When to Enroll for Medicare Advantage Plans in Illinois
Enrollment for Medicare Advantage Plans in Illinois is governed by a series of strict, federally mandated deadlines. Missing these windows can trap you in a bad plan for an entire year.
Your Initial Enrollment Period generally begins three months before you turn 65. Later, the high-stakes Annual Enrollment Period (AEP) occurs every fall, running relentlessly from October 15 to December 7. This is your primary opportunity to safely switch, drop, or add a Medicare Advantage plan for the following year.
Additionally, the dedicated Medicare Advantage Open Enrollment Period runs from January 1 through March 31. During this highly specific window, you are granted one chance to switch to a different MA plan or retreat back to Original Medicare.
Because life is chaotic, Medicare provides Special Enrollment Periods for major, unexpected life events—such as moving out of your current plan's service area, abruptly losing your employer-sponsored coverage, or suddenly qualifying for Medicaid. Knowing these rigid deadlines is the only way to protect your healthcare access in Illinois.
🤔Medicare Advantage vs. Medigap
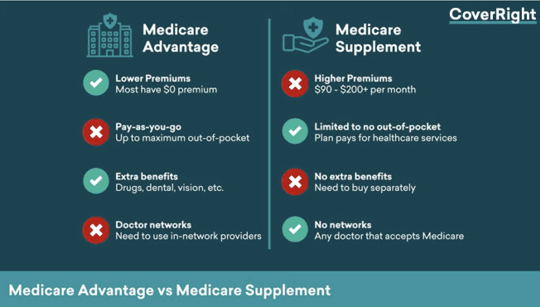
Choosing between a bundled Medicare Advantage (Part C) plan and a Medigap (Medicare Supplement) policy is the most consequential choice you will make for your retirement healthcare. Medicare Advantage efficiently rolls your Part A and Part B benefits into a single, cohesive plan, frequently adding prescription drugs and lifestyle perks.
These bundled plans are historically cheaper month-to-month and drastically simplify your paperwork. The trade-off is control: you must play by the rules of their specific provider networks, which can severely restrict which doctors and hospitals you can use.
Interestingly, Medicare Advantage has a softer foothold in Illinois than in other parts of the country. As of October 2022, only 38% of eligible Illinois residents were enrolled in a private Advantage plan, trailing significantly behind the 2022 national average of 46%.
Conversely, Medigap policies are designed strictly as financial shields. They work alongside Original Medicare to pay the crippling out-of-pocket deductibles and coinsurance that Medicare leaves behind. Medigap provides the ultimate flexibility—you can see any doctor in the country who accepts Medicare—but you will absolutely pay much higher, separate monthly premiums for that privilege.
Here is the unvarnished breakdown of how the two options compare:
| Medigap (Medicare Supplement) | Medicare Advantage (Part C) | |
| Coverage | – Comprehensive, ironclad coverage of almost all out-of-pocket costs. – Total, unrestricted flexibility in choosing your healthcare providers. | – A bundled, all-in-one approach that often bakes in prescription drugs and extras. – Strictly limits you to network providers; you may have to fight for referrals. |
| Costs | – You will face much higher, separate monthly premiums, but drastically lower out-of-pocket medical bills. | – You will enjoy very low or $0 monthly premiums, but risk facing much higher out-of-pocket costs if you get sick. |
| Prescription Drugs | – Historically does not include prescription drug coverage; you must buy a standalone Part D plan. | – Frequently includes prescription drug coverage baked right into the plan. |
| Network Restrictions | – Zero network restrictions. If a doctor or hospital in the U.S. accepts Medicare, you can go there. | – You are handcuffed to the plan's network; seeing out-of-network doctors will cost you severely. |
| Administration | – Requires juggling separate cards and premiums for Original Medicare, Medigap, and a Part D plan. | – Highly convenient; everything is consolidated under a single plan and a single card. |
| Flexibility | – Ultimate peace of mind to travel nationwide and receive top-tier care anywhere. | – Often geographically restricted to doctors in your specific region or county. |
| Additional Benefits | – Strictly focuses on paying medical bills. Does not offer perks like dental, vision, or gym access. | – Frequently lures customers with extra lifestyle benefits like dental, vision, and wellness programs. |
| Decision Criteria | – The best choice if you have a larger budget, travel frequently, or refuse to be told which specialist you can see. | – The smarter choice if you are on a tight, fixed budget, want lower premiums, and are fine using local, network doctors. |
Ultimately, the decision rests entirely on your personal risk tolerance. Choose Medicare Advantage if you prioritize low monthly costs and bundled convenience, and can accept network constraints. Choose Medigap if you demand total freedom in selecting your doctors and want the ironclad security of predictable medical bills, even if it means paying steep premiums upfront.
All Medicare Advantage Providers in Illinois for 2026
- Aetna Medicare
- Blue Cross and Blue Shield of IL, NM
- Blue Cross and Blue Shield of Illinois
- Cigna
- Clear Spring Health
- Devoted Health
- Essence Healthcare
- Health Alliance Medicare
- HealthPartners UnityPoint Health
- Humana
- Medica
- Medical Associates Health Plan
- Molina Healthcare of Illinois
- Quartz Medicare Advantage
- UnitedHealthcare
- Wellcare
- Wellcare by Allwell
- Zing Health